Loan EMI & Prepayment ROI Calculator
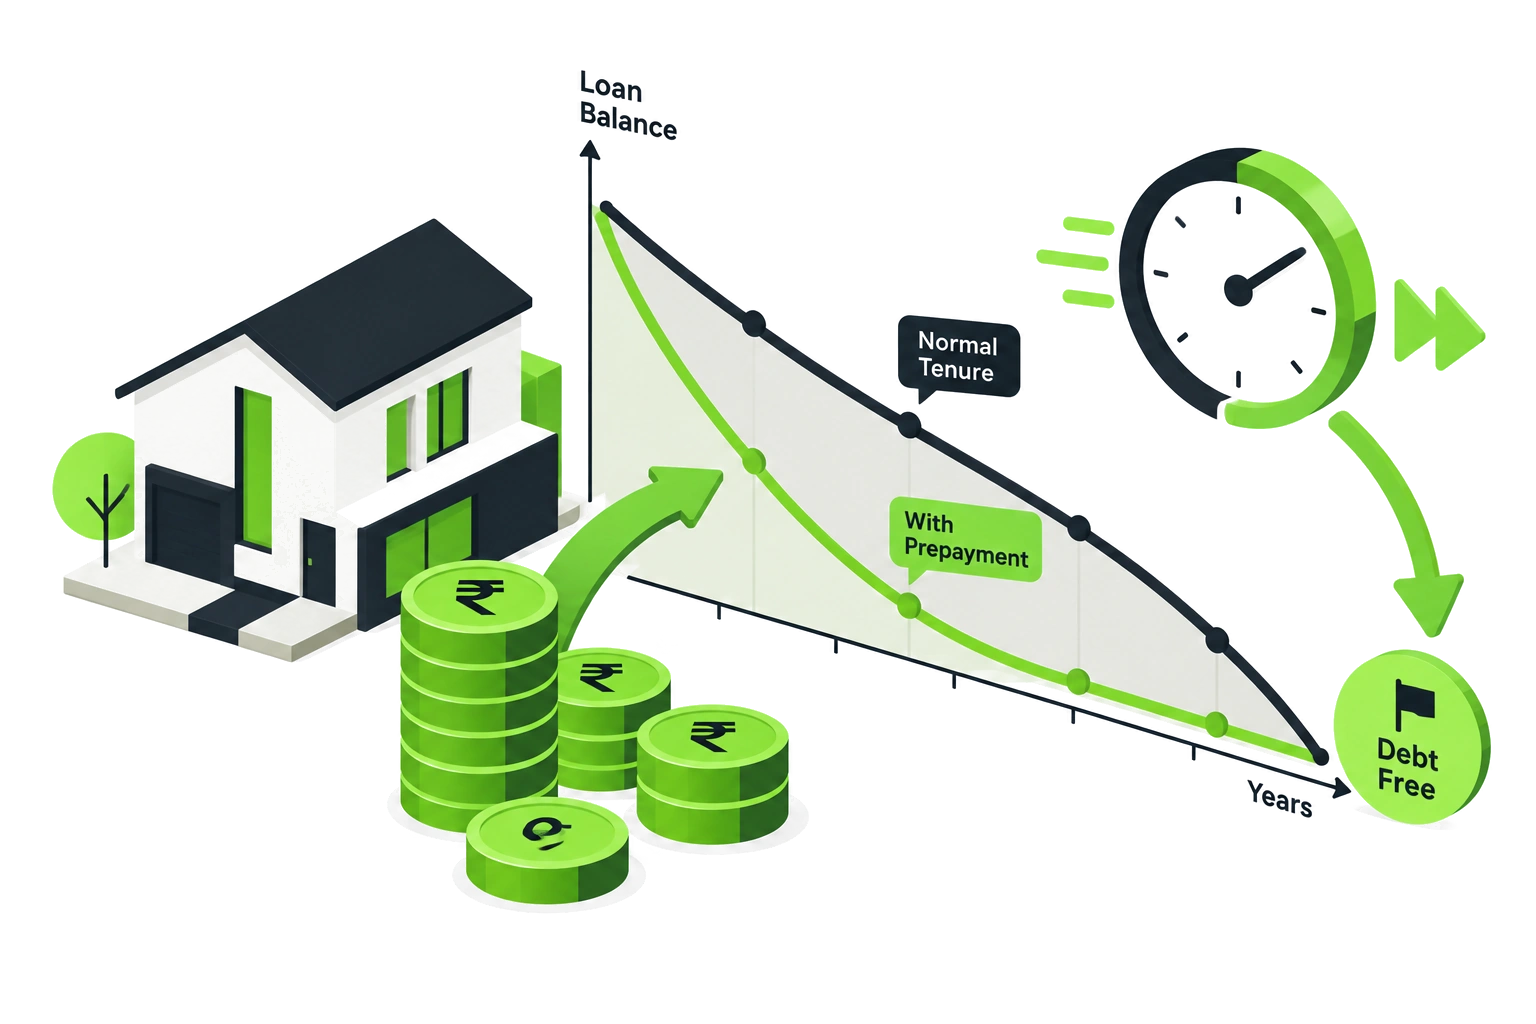
Banks make their highest profits during the first 5 years of your loan when over 75% of every EMI goes toward pure interest. This calculator shows how making targeted early prepayments obliterates compounding interest and cuts years off your debt.
1. Loan Details
2. Prepayment Strategy
With your targeted prepayment plan, your net interest savings is
You cut 22 months (1.8 years) off your loan and save ₹6,11,958 in interest — a saving roughly equivalent to your loan's own 8.75% rate, subject to your lender's terms and any tax treatment that applies to you.
Effective Prepayment Return
Every rupee you prepay saves you a compound 8.75% interest that would otherwise go straight to the bank. That makes prepayment roughly equivalent to a 8.75% return on that rupee — subject to your lender's terms and any tax treatment that applies to you — worth comparing against your other options.
Amortization & Balance Schedule
Year-by-year principal paydown, interest paid, and early closure trajectory.
| Year | Opening Balance | Principal Paid | Interest Paid | Prepayment | Closing Balance |
|---|---|---|---|---|---|
| Year 1 | ₹40,00,000 | ₹77,230 | ₹3,46,952 | — | ₹39,22,770 |
| Year 2 | ₹39,22,770 | ₹84,265 | ₹3,39,916 | — | ₹38,38,505 |
| Year 3 | ₹38,38,505 | ₹91,941 | ₹3,32,240 | ₹2,00,000 | ₹35,46,564 |
| Year 4 | ₹35,46,564 | ₹1,18,536 | ₹3,05,645 | — | ₹34,28,029 |
| Year 5 | ₹34,28,029 | ₹1,29,334 | ₹2,94,847 | — | ₹32,98,695 |
| Year 6 | ₹32,98,695 | ₹1,41,116 | ₹2,83,066 | — | ₹31,57,579 |
| Year 7 | ₹31,57,579 | ₹1,53,971 | ₹2,70,211 | — | ₹30,03,609 |
| Year 8 | ₹30,03,609 | ₹1,67,997 | ₹2,56,184 | — | ₹28,35,612 |
| Year 9 | ₹28,35,612 | ₹1,83,301 | ₹2,40,881 | — | ₹26,52,311 |
| Year 10 | ₹26,52,311 | ₹1,99,998 | ₹2,24,183 | — | ₹24,52,313 |
Frequently asked questions
EMI = P × r × (1+r)ⁿ ÷ ((1+r)ⁿ − 1), where P is the loan principal, r is the monthly interest rate (annual rate ÷ 12 ÷ 100), and n is the number of monthly instalments. This gives a fixed monthly payment that fully repays the loan, with the interest portion highest in the early months and the principal portion growing over time.
Most lenders let you choose. This calculator assumes you keep your EMI fixed and let the extra payment shorten your tenure, since that saves more total interest than reducing the EMI while keeping the same tenure. Check with your lender which option they apply by default.
It depends on your loan's interest rate versus what you'd realistically earn after tax on the alternative. Prepaying a loan at 8.75% is a certain saving at that rate; an equity investment might average more over the long run but isn't guaranteed and carries risk the loan saving doesn't. Compare using the SIP calculator with your own assumptions before deciding.
For floating-rate loans to individual borrowers, RBI rules generally prohibit prepayment penalties. Fixed-rate loans and loans to non-individuals may still carry a penalty — check your loan agreement's foreclosure clause before prepaying a large amount.