Chit Fund Real Interest Rate Calculator
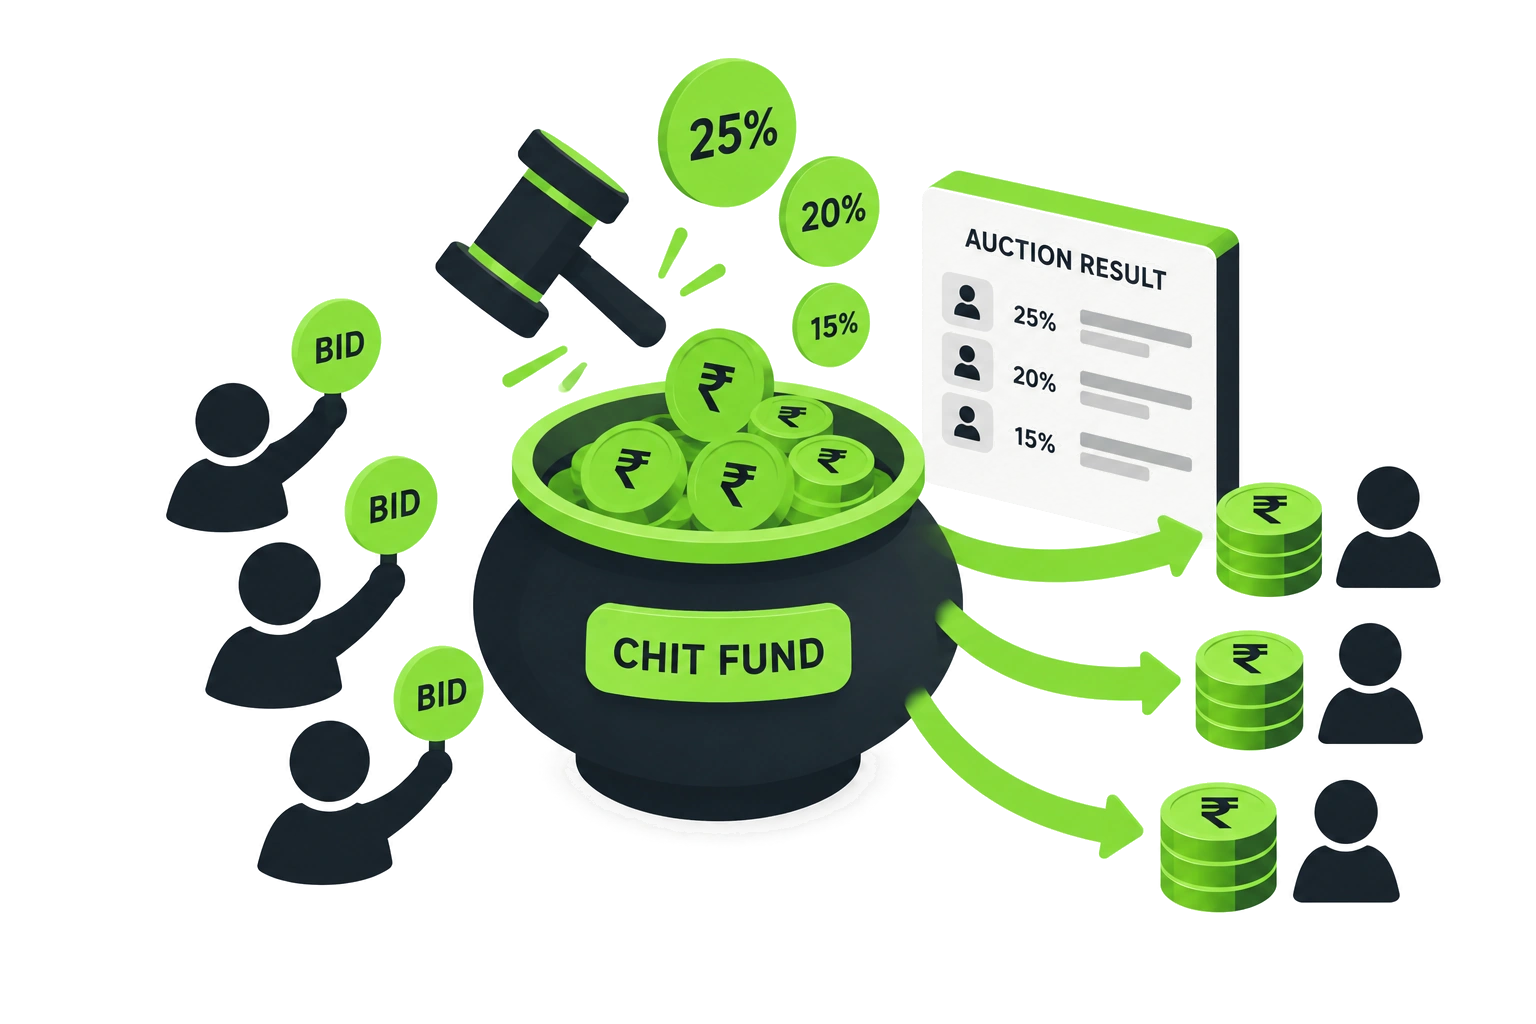
Chit funds blend borrowing and saving into a single pot. This calculator computes your true borrowing APR (as a bidder) or real XIRR return (as a saver), comparing it directly against personal loans and bank fixed deposits.
1. Select Your Role in the Chit
2. Chit Group Details
Winning in Month 4, your effective borrowing rate is
Borrowing in Month 4 costs 29.8% effective APR. A standard bank personal loan at 11.5% is cheaper by 18.3 percentage points.
Inline Math Proof · How This Is Calculated
We solve for the exact Internal Rate of Return (IRR) across all 25 irregular monthly cash flows, treating the winning month's prize as an inflow (+₹3,75,000) and monthly installments as net outflows after dividend discount.
Month-by-Month Cash Flow Schedule
Complete breakdown of nominal due, distributed dividend, and net outflow.
| Month | Nominal Due | Dividend Credit | Net Outflow | Net Cash Flow |
|---|---|---|---|---|
| Month 1 | ₹20,000 | ₹0 | ₹20,000 | ₹-20,000 |
| Month 2 | ₹20,000 | ₹3,833 | ₹16,167 | ₹-16,167 |
| Month 3 | ₹20,000 | ₹3,667 | ₹16,333 | ₹-16,333 |
| Month 4 PRIZE WON | ₹20,000 | ₹3,500 | ₹16,500 | +₹3,58,500 |
| Month 5 | ₹20,000 | ₹3,333 | ₹16,667 | ₹-16,667 |
| Month 6 | ₹20,000 | ₹3,167 | ₹16,833 | ₹-16,833 |
| Month 7 | ₹20,000 | ₹3,000 | ₹17,000 | ₹-17,000 |
| Month 8 | ₹20,000 | ₹2,833 | ₹17,167 | ₹-17,167 |
| Month 9 | ₹20,000 | ₹2,667 | ₹17,333 | ₹-17,333 |
| Month 10 | ₹20,000 | ₹2,500 | ₹17,500 | ₹-17,500 |
Showing first 10 of 25 total months. Full cashflow series evaluated for exact XIRR convergence.