The calculator that takes your side.
Not “your EMI is ₹24,315” — but “you'll pay ₹6.4 lakh in interest, and prepaying ₹2 lakh in year 3 cuts that to ₹4.1 lakh.” Every tool ends with the verdict brokers won't give you.
- Every formula shown, nothing hidden behind a paywall
- No affiliate links — the verdict can go either way
- No account, no email, no tracking your numbers
- New calculator shipped every week, in the open
HOW IT WORKS
Put in your real numbers
Chit value, tenure, your bid or the rate you were quoted — whatever the calculator asks for. Nothing saved, nothing signed up.
Get the verdict, not just a number
Every result ends in plain English: what you're really paying, and how it stacks up against the obvious alternative.
Check the full math
Every formula is shown inline. Don't take our word for it — verify it, or use it to make your case to a bank or a broker.
Calculators that give you a verdict, not just a number.
Brokers and banks give you complex tables that end with “Apply Now”. ReturnDesk runs the exact math, compares against standard alternatives, and tells you plainly whether the numbers work in your favor or against it.
Prepaying ₹2 Lakh in Year 3 on a ₹40L home loan saves you
You shave 4.5 years off your loan and save ₹5.24L in interest — a saving roughly equal to your loan's own 8.75% rate, subject to your lender's terms.
Prepaying early avoids more compounding interest than prepaying later, since it acts on a larger remaining balance for longer.
THE DESK, IN BUILD ORDER
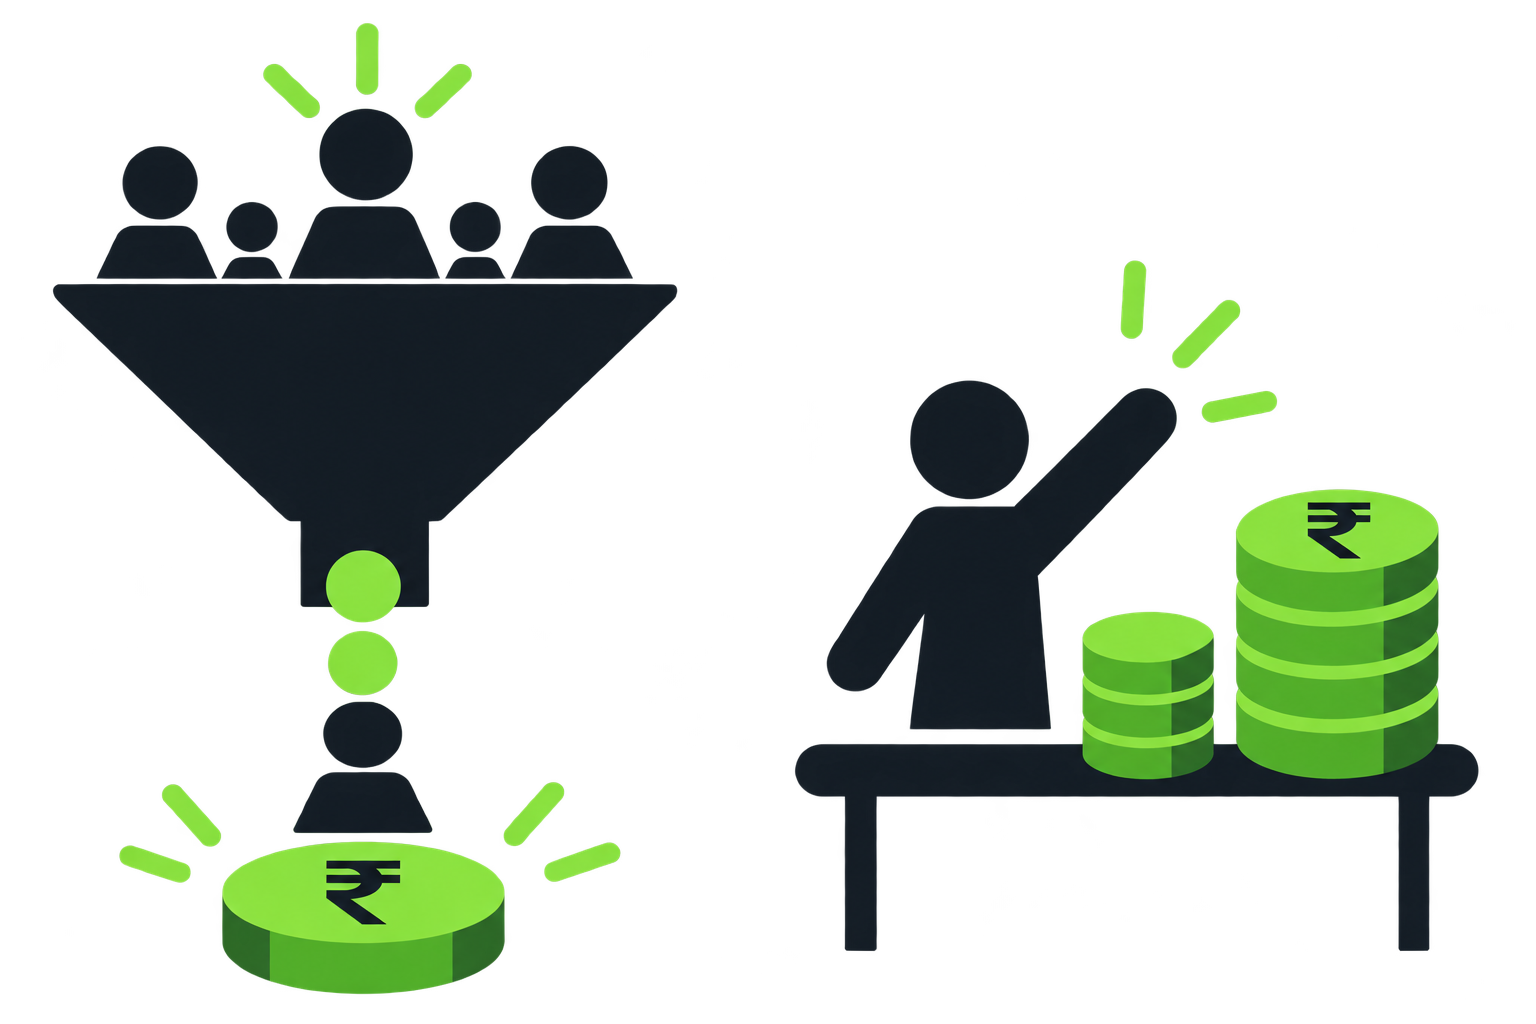
We can say “the FD wins” because we don't sell the fund.
Groww, Zerodha, ClearTax — their calculators are funnels into their products. Every result nudges you toward something they sell. returndesk has no product, no fund, no brokerage, so the verdict can go either way — even when it means telling you to walk away and put the money in a plain FD instead.